|
By Brenda L. Peterson, The Layoff Lady My New BookCareer Opportunity Readiness: The Layoff Lady Guide on Evolving from Hope to Career Resilience to the CEO of You is coming out this month! Here’s what motivated me to write this new book. It Started With Layoff LessonsMy first book, Seven Lessons From Seven Layoffs: A Guide, was written for a specific audience. It was meant to help people who had just been laid off navigate unemployment, find a new job, and overcome obstacles along the way. Early on, I realized that much of this content was relevant to those who were still happily employed. Even so, I found that many people could not bring themselves to read a book about layoffs. Even thinking about an unplanned job loss felt like it might tempt fate and make it happen to them. The Emotional Impact of Unplanned Job LossI have had countless conversations with the newly unemployed. Those hit hardest by the news genuinely didn't believe their employer would eliminate their position. Many had worked for the same organization for a decade or more, had not updated their resume in years, and assumed they would have that job until they decided to retire. They kept their heads down, did quality work, and counted on the company to look out for them. When their jobs ended, many had no idea what to do. In a world where people ask about your livelihood early in a conversation, having no good answer was unnerving. Even those who didn’t think work was very important to them felt the loss when that key piece of their identity, the job title bestowed upon them by a company, was gone. They had never thought about their job as a business arrangement, decided what they actually wanted from their work, or considered the difference between company needs and their needs as an employee. After years of outsourcing their career plan to their employer, they realized they were on their own. From Post-Layoff to ProactiveI knew I needed a better way to talk about these concepts. Instead of scare tactics, I wanted a more empowering approach that informed people and positioned them for success. I shifted my message from being reactive to proactive. The world of work keeps evolving, and those changes create challenges and opportunities. I reimagined how these ideas could help people navigate both options. Why I Wrote This Book That is what led me to write Career Opportunity Readiness. My goal was to help people better understand the realities of the employee/employer relationship and build habits that could help them actively manage their work and their lives instead of just hoping for the best.
This new book covers how to build Career Resilience by highlighting your value so you’re better prepared to navigate disruptions to your work. Then, it focuses on being proactive, including defining success for yourself and staying open to opportunities that can help you build the work and life you want.
0 Comments
By Brenda L. Peterson, The Layoff Lady Energy Management Beats Time ManagementMany people equate productivity with making progress on a task list. When you're going through a trying time, everything can feel harder. Whether you are navigating family drama, work burnout, or a post-layoff job search, there will be times when you can't just "buckle down" and get things done--no matter how efficient your to-do list is. Managing your energy levels, not just your ever-growing task list is the key to making progress. Reflect on Your Time and Your EnergyAs you think about how to spend your time, learn about yourself and when you will be the most productive and happiest with each activity. I interact with LinkedIn posts during my first cup of coffee, enjoy afternoon walks, and do yoga at night before bed. There are no absolute right or wrong times for many things, just ones that are a better fit for you. Your Most and Least Productive Times of DayTake time to reflect on your most and least productive times. Use these questions as a starting point:
Remember, there are no right or wrong answers, just what is true for you. Factors Influencing Your Energy LevelsIn addition, reflect on the following factors and their impact on your energy levels:
Remember, there are no right or wrong answers, just what is true for you. Patterns for Energy Builders and Energy DepletersBased on your responses to those questions, you may have identified factors that energize you and those that deplete you.
Knowing these things about myself helps me know how to organize my time to maximize my energy. Letting family and friends know what I need also helps them understand and support me as I work towards my goals. Self Care Builds EnergyAfter you identify your energy depleters, here are a few steps you can take to build your energy:
Leverage Your Energy To Achieve MoreWhen I identify my energy patterns and take steps to recover when needed, I have more capacity. Having my energy in a good place helps me accomplish more in less time. Then, I can leverage my to-do lists and make real progress towards my goals. Learn More
By Brenda L. Peterson, The Layoff Lady Post-Layoff ChangesWhen your “day job ends,” many things in your financial life change. For one, what is for many people their primary source of income, ends. This often prompts a quick shift to a short-term "survival" mindset that will last from the layoff event until the first paycheck from that new job arrives. Let's talk about your new financial goals and how to manage expenses. Disclaimer: (You know there has to be one of these now that we're talking about topics like personal finances and health insurance.) While I know quite a bit based on my previous work experience supporting financial coaches, my own research, and my personal life experiences, I do not currently hold a license or certification to give financial advice. Therefore, the information provided here is educational information provided as guidance. I hope you can glean value from my lessons learned. Feel free to take my recommendations or not—but whatever you do, double-check my facts (and everyone's facts, for that matter). This is your life, and you will care more about your finances and health care than anyone else. With that, read on. Employed Financial GoalsWhen gainfully employed, your household financial goals may look like this:
Typically, goals include living within your means and spending/saving/giving money in line with your values and financial priorities. When things are going "as normal," you probably have the capacity to think about current activities and consider what is possible in the future. Layoff Financial GoalsDuring a career transition, financial priorities shift from being proactive to focusing on the here and now. The goal is to get through the next one to six months with as few adverse effects as possible. Here are my recommendations for crucial goals to keep in mind during a period of reduced income and job transition:
While navigating post-layoff unemployment, the goal is to make it through with as few bumps and bruises as possible. Instead of trying to pay off a previous purchase or save for a goal, you will probably leave any “extra” money in your checking account just in case. Paring Down ExpensesThis is also a good time to see what expenses you can pare down in the short term to ensure that the money you do have lasts a little longer. Here are a few ideas:
Prioritizing ExpensesHere is a recommendation for prioritizing which bills you pay when money is tight:
What To Do If You Can't PayIf you can’t pay your bills, call the company and discuss how to make arrangements. Instead of just plain NOT paying a bill, make a phone call. I know this can be hard and humbling, but it is important to figure out a plan. Remember, you're not the first person to be in a position where they had an unexpected job loss and needed to figure out alternatives. It is also to the company's advantage to work with you. It's in the company's interest to help you stay on track as a customer than for them to spend the time and staffing on repossessing items or turning off and on utilities. Help them help you. Making this call also helps minimize damage to your credit score (which could even impact your ability to find work sometimes). Be sure to call right away when you start to have issues instead of waiting until you have a lot of issues. I encourage you to call when you worry abouat having a hard time making one mortgage payment instead of waiting until you are months behind. Remember, though, even if you have waited, MAKE THAT CALL! When working with a company on making payment arrangements, you may be able to defer payments, figure out a payment plan, take advantage of a company-sponsored program, or find a government-sponsored program to help you during a hard time. County, faith-based organizations, and non-profits may be able to help you, too. Whether you need help paying for gas, food, transportation, or utilities, make sure to use the available resources. Learn More
By Brenda L. Peterson, The Layoff Lady Your Salary RequirementsMost of us work so we can pay for our lives. When you are job searching, it’s important to determine your target salary range to make your job search more effective. Having this information will help you prioritize which jobs to apply for and help you have those early salary conversations. Let’s look at a few strategies for answering the question, “What are your salary requirements?” Start With Your Target RolesFirst, ensure you’ve done the requisite amount of soul-searching to determine what you want to be next in your career. Have a list of what you want to do, possible job titles, relevant skills, core responsibilities, daily activities, focus areas, types of companies, and industries. Having these details on your desired job will help as you start to do salary research. The DisclaimerWhile I feel comfortable discussing various financial and insurance concepts, I do not currently hold a license or any certification that deems me inherently qualified to give financial advice. The information provided here is intended to be used for educational purposes only. Sometimes, the core challenge is knowing how a system generally works, the terms used to describe what you’re asking about, and where to go for additional help. My goal for this article is to share information to guide you as you navigate the murky waters of job searching. I hope my personal experiences can help you cut a path through the wilderness as you try to figure out your next steps. Feel free to take my recommendations or not. Whatever you do, double-check my facts--and everyone's purported facts, for that matter. This is your life, and you will care more about your financial and healthcare decisions than anyone else. Use this information as a starting point for further research as you ultimately decide what’s right for you. Identify Your PrioritiesNow that you understand your target job and what that looks like, think about what you value in a job. For example, some may prioritize having a specific job title, receiving tuition reimbursement money to earn their next credential, and opportunities for a promotion within the company. Another person may prioritize having interesting work while also having schedule flexibility, the ability to work remotely most days, and low health insurance premiums. Still another person may prioritize alongside colleagues in an office, having the opportunity to mentor new employees, and finding a job they can keep for the next 20 years. Think about what is the most important to you. In addition, think about what you value in an employer. Working for a non-profit, government entity, start-up, family business, or Fortune 500 company will have salary, benefit, job security, and total compensation-related implications. Overall, think about what matters to you, and be aware of the salaries that align with your overall job preferences. Factors That Influence Your Target Salary RangeWhen considering your salary requirements, I suggest using a range instead of one specific number. Let’s look at strategies for determining your target salary range. Here are numbers you might have in mind that could impact your range:
I suggest the salary range you share with potential employers includes the lower number that is the minum salary you would happily accept and the maximum number is what you'd be really excited about. What Companies Are PayingKnowing what companies are paying for what you do should also factor in to your target salary range. Here are a few strategies for finding out more: Search For Openings in Pay Transparency StatesTake these steps to find out what open positions are paying:
Research Your Job Title and Geographic LocationMany websites have salary information. Two that come highly recommended by recruiters are Salary.com and Payscale.com. In fact, Salary.com has a Know Your Worth calculator where you can add details like your job title, location, education level, and years of experience and see the impact each factor has on your potential market value. Ask AroundFind out from other job searchers, recruiters, and hiring managers what salaries companies are paying for specific roles. You can also inquire with professional development organizations to see if there are industry or job-specific studies available that include salary-related information. Confounding FactorsHere are a few factors that might make this process challenging:
Learn More
By Brenda L. Peterson, The Layoff Lady Contract vs Benefits Eligible RolesKnowing your ideal salary upfront helps you focus your job search on roles that meet your expectations — and avoid wasting time on ones that don’t. If you are looking at contract positions, the salary you will receive is the same as your base salary. Usually, you are paid a set amount for each hour worked with no additional benefits. Consequently, contract positions often have a higher hourly rate. However, if you are in a benefits-eligible role, you will receive additional value above and beyond your base salary rate. Let's consider what may be included in your total compensation package. A DisclaimerWhile I feel comfortable discussing various financial and insurance concepts, I do not currently hold a license or any certification that deems me inherently qualified to give financial advice. The information provided here is intended to be used for educational purposes only. Sometimes, the core challenge is knowing how a system generally works, the terms used to describe what you’re asking about, and where to go for additional help. My goal for this article is to share information to guide you as you navigate the murky waters of job searching. I hope my personal experiences can help you cut a path through the wilderness as you try to figure out your next steps. Feel free to take my recommendations or not. Whatever you do, double-check my facts--and everyone's purported facts, for that matter. This is your life, and you will care more about your financial and healthcare decisions than anyone else. Use this information as a starting point for further research as you ultimately decide what’s right for you. Your Work IncomeFirst, let’s look at a high-level, generalized overview of the money you may receive:
Employer Money For A Specific PurposeIn addition to receiving money in the form of a check or payment payable to you, you may also receive money from your employer that is earmarked for a specific purpose.
Benefits, At Least Partially Employer PaidIn the United States, many people obtain different types of insurance through their workplace. Employer often pay administration costs of the plan and help cover some of the costs. Here are some of the typical benefits available:
Access To Purchase Additional BenefitsMany employers offer the option for employees to purchase additional benefits. These can include vision insurance, enhanced disability coverage, supplemental life insurance, spouse life insurance, child life insurance, accident insurance, condition-specific health insurance, a legal protection plan, or orthodontic benefits. PerksCompanies may also offer a variety of perks. These can include items you can purchase for a lower cost or resources you can take advantage of that you might otherwise pay for elsewhere. These could include an onsite gym, onsite daycare, free parking, entertainment discounts, stamps, bus passes, use of the company van, cell phone plan discounts, or reduced entry fees for area attractions. Perks can also be anything that makes work easier, more engaging, or more pleasant. These could include shift bidding, flexible work arrangements, remote work, work-from-home days, summer hours, four-day workweeks, onsite flu shots, overtime opportunities, or company events. Time OffEmployers also often pay you for specific hours when you do not work. Here are a few standard categorizations for different types of paid time off: paid time off (PTO), sick time, vacation time, paid holidays, floating holidays, volunteer time, bereavement leave, jury duty pay, or military leave. Instead of having a specific number of paid days available for sick or vacation time, some companies have unlimited time off policies. In most cases, instead of earning and then choosing to use paid time off, you work with your manager whenever you want to take off. In general, as long as you are performing your job to an acceptable level, you can take time off. The Salary Question: RevisitedKeep in mind that when a recruiter asks for your salary range, it’s not just about base pay. Benefits, bonuses, and other perks can significantly impact your overall compensation package. This is also why I suggest that candidates provide a salary range rather than a fixed number. Learn MoreBy Brenda L. Peterson, The Layoff Lady Post-Layoff ChallengesWhen your “day job" ends, many things in your financial life change. For one, what is for many people their primary source of income, ends. This often prompts a quick shift to a short-term survival mindset that will last from the layoff event until the first paycheck from that new job arrives. After you think about your overall survival budget goals and managing expenses, think about your sources of income during your career transition. Disclaimer: (You know there has to be one of these now that we're talking about topics like personal finances and health insurance.) While I know quite a bit based on my previous work experience supporting financial coaches, my own research, and my personal life experiences, I do not currently hold a license or certification to give financial advice. Therefore, the information provided here is educational information provided as guidance. I hope you can glean value from my lessons learned. Feel free to take my recommendations or not—but whatever you do, double-check my facts (and everyone's facts, for that matter). This is your life, and you will care more about your finances and health care than anyone else. With that, read on. Income While WorkingWhen you’re gainfully employed, usually a couple of times per month, you receive your paycheck. Your taxes are deducted according to what you set up. You also typically have deductions for health care costs, company-sponsored insurance benefits (life insurance, disability insurance), and company-sponsored savings (Flexible Spending Accounts, Healthcare Savings Accounts, retirement contributions). Once that company no longer employs you, your income changes significantly. Possible Money From Your Employer After LayoffWhile you won’t have the income from your job on a go-forward basis, you may have one or more of these types of money coming from that employer after your position ends. Your Last PaycheckYou will receive a payment for any hours worked for which you still need to be paid. Typically, this check will not include deductions for health insurance or any other benefits since you no longer participate in those programs. In addition, taxes will be withheld from this payment. Remaining Paid Time Off (PTO) or VacationDepending on multiple factors, you may be paid for any PTO you had accrued but had not yet taken. For example, if the company you worked for had “Unlimited” paid time off, you will not receive any vacation payout since there was no tie between accruing and taking time off. In addition, some companies have written into their company policies that they do not pay out vacation time after an employee no longer works there. However, some states require vacation payouts from previous employers. (I know this because Nebraska, my current state of residence, is one of those states.) Know that getting a payout is not guaranteed, but this is definitely something you should investigate to see if you are eligible. A Severance PackageA severance package may be a component of your layoff. Severance could include a lump sum, continuation of insurance for a period of time, and/or support services to help you transition to a new position outside of that organization. In many cases, companies do not have to provide any sort of severance. If they offer severance, it is often to help minimize the likelihood of former employees taking legal action after a layoff. It is also a way that companies help their employees financially during that difficult transition time. If you do receive a severance payment, the amount can vary wildly. It could be between a fat lot of nothing, to the equivalent of a paycheck, to 1-2 weeks of pay for each year you were with the organization, to a larger check equaling months of income. It depends on the organization, their financial position, how they want to be perceived by the media during the layoff, or any other factors. If you receive a severance payment, realize that it may be less money than you anticipated because of withholding taxes. If you are offered a severance package, realize you must sign something before receiving a payment, benefits, or any other services promised. Once you sign, any thoughts you might have about legal action regarding your employment with the organization are pretty much over. Read the agreement given to you, consider having a lawyer look it over, and ask for clarifications (and any revisions) before signing it. After that, there is typically a waiting period before you receive that money. This is big-time adulting here, so enlist help as needed. Unemployment Insurance (UI) BenefitsWhile your regularly scheduled income from your previous employer ends, in most cases, with a layoff, you will be eligible for unemployment insurance (UI) benefits. In short, apply for UI benefits. Remember--the money that pays unemployment benefits comes from taxes employers (and in a few states, employees) are required to pay for this specific purpose. You're not abusing the system when you take advantage of unemployment benefits. You're using a valuable benefit that is set up specifically to help people through what can be a rough transition. UI BasicsHere are a few key details about UI payments:
Additional Factors That Impact UI Benefits PaymentsYou may also be eligible for job search support services and even programs to help you upgrade your skills. In many states, you must complete outlined “reemployment activities” to stay eligible to receive unemployment payments. For example, some states may require you to apply for a given number of jobs each week, or attend classes, or confirm you did not turn down a suitable job offer. Also know that if you will be receiving a severance payment, it will impact when you are eligible to start receiving unemployment payments. When you apply for unemployment, you will be asked to specify any payments you still expect to receive from your previous employer. Typically, if you are receiving severance that is intended to cover a set period of time, you will also not be eligible for unemployment payments during that time. Personally, I had periods when I was in a career transition where I never received an unemployment payment because I started a new job before the number of weeks specified for my severance ran out. Again, if you’re unsure on details, make that phone call to ask for clarification. Interim Paid WorkDepending on your situation, you may need to find interim work while looking for a more permanent role. For example, if the amount you receive from UI benefits needs to be increased to pay your core bills, you may need to take a job to make ends meet. This could be anything from contract work in your chosen field (that may pay pretty close to your previous full-time job) to a supplemental job that you do for a little extra income. If you have a partner, it may be a case where they take on additional paid work or help more with expenses while you are in career transition. Other OptionsThere are multiple ways to pay for your life, varying from good to decidedly bad ideas. You could do anything from using your savings, to selling unused items, to using credit cards, to acquiring additional debt, to using your home equity, to taking money out of your HSA account (and paying taxes on what you removed), to starting a Go Fund Me page, to donating plasma, or even tapping into retirement accounts (and paying a steep penalty). Be sure to consider the short and long-term implications of any of those decisions before choosing your course of action. Learn More
By Brenda L. Peterson, The Layoff Lady Post-Layoff ChallengesWhen your “day job ends”, many things in your financial life change. For one, what is for many people their core source of income, ends. This often prompts a quick shift to a short-term survival mindset that will last from the layoff event until the first paycheck from that new job arrives. Let's talk about how to manage your healthcare during this time. Note that I’ll outline options first, and then you can review all of the links at the end of this article for additional information. Brace yourself—there is a lot going on here. Disclaimer: (You know there has to be one of these now that we're talking about topics like personal finances and health insurance.) While I know quite a bit based on my previous work experience supporting financial coaches, my own research, and my personal life experiences, I do not currently hold a license or certification to give financial advice. The information provided here is educational information provided as guidance. I hope you glean value from my lessons learned. Feel free to take my recommendations or not—but whatever you do, double-check my facts (and everyone's facts, for that matter). This is your life, and you will care more about your finances and health care than anyone else does. With that, read on. Healthcare Coverage While EmployedIn the United States, where health insurance for many people is part of an employer-provided benefits package, thinking through the health insurance implications of a job change is critically important. While working, you have limited health care coverage options through your employer. You make your selection when you first start, and after that, once a year. In most cases, your employer pays for part of it, facilitates the payment for your health care coverage, and even allows you to set up and use a Health Savings Account (HSA) as a separate benefit. Healthcare Coverage Options After a LayoffAfter you are laid off, your former employer will let you know when your benefits end. It may be as soon as your separation date, the end of the calendar month, or some other date altogether depending on your organization. If you have the time and ability to do so, it may be a good idea to fit in any doctor's appointments you have been putting off while you still have coverage. Once your employer-sponsored coverage ends, there are many options for healthcare coverage. You'll also need to take steps to enroll in whatever coverage you choose. Most of these options have an associated monthly premium, and some are more cost-effective than others. Here are a few possibilities for your consideration. Your Severance Package and Continued BenefitsIf you do receive a sewerage package, you may also receive continued healthcare coverage for a specified period of time. You may get health care coverage included for a bit. This could be the company paying for the benefits you had before, or an amount of money that is earmarked to pay for healthcare coverage. These are two very different propositions. If the company continues to pay for your health benefits, your coverage will work as before with your same coverage levels and networks. However, if you receive money to pay for health care coverage, you will need to decide what to purchase, enroll, then pay for it as billed. COBRA Continuation CoverageCOBRA stands for Consolidated Omnibus Budget Reconciliation Act. In short, this provision allows former employees to pay the total cost of their formerly work-sponsored health insurance on their own. If you choose this option, you can keep this coverage for up to 18 or 36 months. As part of your layoff paperwork, your now former company will send you information about the logistics and cost of keeping this coverage and let you know your deadline for signing up (which is typically 60 days). The good news? You can keep your same coverage. The bad news? The cost may knock you back. Now, you'll pay the total price for your coverage instead of your employer helping offset the cause. For example, while working, you may have spent $500 a month for your family’s healthcare coverage, and with COBRA, you will now likely pay thousands of dollars a month for that same coverage. A Dependent on Someone Else's Employer PlanDepending on your age and personal situation, you may have the option to be added to someone else’s employer-sponsored healthcare coverage. Here are two common scenarios:
In general, if your former employer’s plan covered you, your family member's plan will allow you to enroll in their plan, even mid-year. Be sure to check with your family member's employer to see if being added to their plan is a good option for you. Remember, if you are added to your family member's health insurance plan, the additional costs for whoever is footing the bill can vary from “no big deal” to “holy crap, that’s an extra [whole lotta money] a paycheck!” Healthcare.gov: The MarketplaceSince the Affordable Care Act (ACA—also nicknamed “Obamacare”), additional healthcare coverage options have been available outside employer-sponsored coverage. To find out what health insurance options are available, your eligibility, and any amount of help (in the form of a subsidy) you might qualify for, check out Healthcare.gov, also referred to as “The Marketplace.” Alternatively, some states have their own healthcare-specific website, like MNsure.gov in Minnesota. Regardless of if your state uses the national site or their own, this is the go-to place to find out about possible healthcare options that comply with ACA standards, meaning that they include a base level of coverage (like preventative health screenings, emergency services, pregnancy, etc.). Many of these plans are High Deductible Health Plans (HDHP), and the higher the deductible, the lower your monthly premium, but the higher the possible out-of-pocket expense you will have. As with other high deductible plans, you can save money in a separate Health Savings Account (HSA) to help cover those expenses. However, Healthcare.gov does not have the option to help you set up an HSA account, so you’ll have to seek that out elsewhere if you are interested in setting that up. One significant benefit of looking here is the possibility of getting a subsidy. A subsidy will help offset your healthcare cost and is usually applied before any premium you would need to pay every month. Typically, subsidies are calculated based on your projected income for the year, depend on how much money your household is bringing in, and may vary by state. You would need to enroll in an ACA plan within 60 days of being laid off. Overall, Healthcare.gov can be a lot to juggle—but they do have help available in the form of agents, brokers, or assisters. Short Term Health InsuranceShort Term health insurance is just that—lower-cost insurance intended to help you bridge the gap between employer-sponsored coverage. Typically, these don’t have preventative benefits (like annual physicals or flu shots covered), but they are significantly less expensive. In addition, this kind of coverage ensures that if something big happens, like an accident where you end up in the hospital, you won’t go broke paying for all those costs. For example, during one period of unemployment, I bought short-term health insurance coverage for my daughter (for a tumultuous month where for a moment, it looked like all of my daughter’s parental units would manage to be out of work all at once). It was under $100 and ensured she had at least some coverage as we figured out the details of her longer-term healthcare coverage. Other OptionsThere are several other options to help pay for healthcare costs varying from good ideas to decidedly bad ones. For example, you could buy a private health insurance plan, take part in Medicaid/Medical assistance based on your financial situation, explore a community health share program, visit community health centers, use telehealth, rely on Minute Clinic, use a healthcare-specific credit card, and/or use discount cards to minimize prescription costs. When it comes down to it, consider the short and long-term implications of your healthcare coverage decisions (including the possible financial hardship of having a significant medical diagnosis or expense without being insured) before choosing your course of action. Learn More
by Brenda L. Peterson, The Layoff Lady Learning About YourselfThe first step of job searching is figuring out what kind of a role you even want. Instead of jumping right into the job you did before, taking a little time for introspection is wise. One good step in this process is finding out more about your strengths. Learning about what you are good at--and how to tell the story of your talents and successes--can help you position yourself well as you apply and interview for a new role. People Are Good at Different ThingsIf you ask many people what they are good at, they would need help putting their natural abilities into words. Taking the StrengthsFinder assessment was a great starting point for me to better understand what I do well. Often, individuals are blind to their own unique talents. In the past, I have wrongly assumed that EVERYONE does the things I do. Like (of course) everyone takes notes regularly in everyday conversations when they learn something--and (of course) everyone makes a seating chart whenever they are in a group of new people to remember names. Turns out--NOPE! These are things I did that not everyone does. This was a huge breakthrough for me. So how do you figure out what you do that not everyone does? Part of the Answer: CliftonStrengths AssessmentThe CliftonStrengths Assessment (previously known as Clifton StrengthsFinder) is a wonderful tool for identifying what you are good at, how that manifests, and how your version of each strength shows up. The 30-minute online assessment includes 177 questions, including paired statements. Then, on a scale, you select which of the statements is more like you. From there, you'll receive a report identifying your top five strengths along with a more detailed description of how those strengths are exhibited in how you interact with the world. Reading a report about yourself (one that is freakishly accurate, by the way) is downright life-changing. After taking the assessment, you'll be able to see your unique talents and have language to explain how what you do sets you apart from others. Having a way to put your abilities into words can translate directly into your resume and how you talk about who you are and what you bring to the table. More Strategies for Finding Strengths and TalentsHere are a few other strategies for identifying what you're good at and how you show up in the world:
Learn MoreBy Brenda L. Peterson, The Layoff Lady What You WantIn a previous article, we discussed the value of knowing what you want, what you don’t want, and what would be acceptable to you. You may also adjust what you want as your job search progresses. Main Factors To ConsiderWhen you put together your target job, it is just that: your target. As you compare your target to the job market, you will continually update your job priorities. Your requirements may evolve depending on the length of your search. Your Acceptable Job May Change Over TimeHere is how your job wants and needs may change over time:
You Can Also Stay the CourseConversely, you may be committed to find a job that very closely aligns with your target job. The good news is that you get to decide what role is right for you, and what will make you happy longer term. The bad news is that it may take you longer if you have very specific requirements and less flexibility. In this case, make sure that you think through options for interim income so you are able to support yourself as you find a role that meets your requirements. Learn More
By Brenda L. Peterson, The Layoff Lady Layoffs Happen All The TimeIt starts like any other day. Then, it takes an ominous turn. Whether you were invited to an ambiguously titled last minute meeting, received an awkward message in your personal email notifying you of your last day, or are perp walked to HR on your first day back from vacation, you are now among the newly unemployed. Welcome to the suck.  Layoffs happen all the time. Now What Do I Do?Even if there were buyout rumors, a quarter with low sales, or a new company direction, being part of a reduction in force (RIF) is still surreal when it happens to you. It's hard to know what to do with yourself when you find yourself unexpectedly out of the job. It's time to redirect your attention. Your New Focus AreasThe work problems you had an hour ago are gone. Along with your freed-up future come very different challenges. It’s time to shift to these top three focus areas:
Your Guiding PrincipleAlong with your new focus areas, your overall guiding principle is not to do anything counterproductive (or downright dumb) as you figure out your post-layoff next steps. Your Don't Do It List Here are the career-limiting moves that will make your life harder. Instead of springing into action, stop, think, and then just don't do the following:
Your Think-Before-You-Consider-Doing List Here are a few things you may want to do at some point, but that require thought and a plan before you move forward. At the very least, sleep on it before you do any of the following:
Now that you are at least somewhat inoculated against creating utter chaos for yourself, let's get back to those top three focus areas. 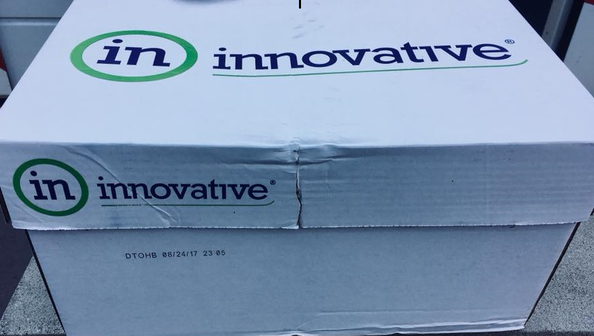 My white box from layoff #4. Focus Area 1: Process Your EmotionsLosing your job can be an emotional roller coaster. An unplanned job change is a stressful life event on par with getting divorced or going to prison. Just like dealing with a death in the family, you’re dealing with the death of the future you thought you had. Losing that imagined future is a significant loss that needs to be addressed. Figure out how you will cope with these changes. While distracting yourself from the unpleasant parts of the process is natural, building healthier coping mechanisms, like prioritizing self-care, is better for your long-term success. While you can get away with avoiding your feelings for a while, eventually, you need to acknowledge each one so you can move on. If you don’t work through those difficult emotions, your ignored feelings will come out sideways at just the wrong time. It is better to work through your grief privately than to fall apart during an interview or snap at someone who is trying to help you. Step 2: Review Your FinancesDisclaimer: While I know quite a bit based on my previous work experience supporting financial coaches, my own research, and my personal life experiences, I do not currently hold a license or certification to give financial advice. Therefore, the information provided here is educational information provided as guidance. I hope you can glean value from my lessons learned. Feel free to take my recommendations or not—but whatever you do, double-check my information (and everyone's facts, for that matter). This is your life, and you will care more about your finances and health care than anyone else. With that, read on. Possible Money From Your Former EmployerAlthough your paychecks will eventually stop, you will receive your final paycheck, possibly vacation time that you have earned and, hopefully, a lovely parting gift from your former employer in the form of a severance package. Severance could be equivalent to a set number of weeks of pay or include an additional lump sum, continuation of some benefits, and job placement services. In most cases, employers do not have to give you any type of severance. If you are eligible for a severance package, you will need to sign something before receiving that money. Once you sign, any thoughts you might have about legal action regarding your employment with the organization are pretty much over. Read the agreement given to you, consider having a lawyer look it over, and ask for clarifications (and any revisions) before signing it. After that, there is typically a waiting period before you receive that money. I also encourage you not just to sign whatever paper they put in front of you. Make sure you advocate for yourself. Unemployment IncomeAfter a layoff, most people will be eligible for unemployment insurance income, or UI. I encourage you to apply for unemployment payments. The money used to make unemployment payments comes from the payroll taxes that employers pay. That money is intended to help people who have been laid off to pay their bills as they search for something new. Unemployment payments are administered at the state level and vary by state. After you apply, there may be a waiting period before you receive a payment. Your state will also outline the amount of each payment you will receive, the number of payments you are eligible to receive, and additional factors impacting your payments. You may also qualify for job search support services and even programs to help you upgrade your skills. In short, apply for unemployment income right away. In most cases, there is not a good reason for most people to forgo unemployment payments. A Note About Health InsuranceSince many people rely on their employers for health insurance coverage, consider how you’ll cover healthcare costs. If you have a spouse, domestic partner, or parent who can bring you onto their health insurance, that may be your best option. Check with the other person’s employer and let them know you no longer have health insurance through your employer because of a layoff. Their employer can talk you through your next steps and cost changes. If that's not an option, consider COBRA coverage through your former employer. This means you could stay with your previous health insurance, but now you'd pay the whole premium cost. Brace yourself when you see your new premium amount because it is usually A LOT more than you spent as an employee. Another option is going on the insurance exchanges at Healthcare.gov to find coverage. You may even be eligible for a subsidy to offset the cost. Alternatively, for less expensive coverage intended to cover a big expensive medical issue should it happen, short-term health care insurance may be a good interim option. Do your research and determine what makes the most sense for you and your household. Step 3: Prepare For Your Job SearchNext, plan to launch your search for a new job. Start by thinking about what kind of job you want. Write down job titles, possible employers, and your target salary range. Update your resume to include details about your last position and showcase your unique skillset as it aligns with your target job. From here, start letting people know your new status of being “in transition” and ask for help. They might be able to introduce you to a valuable business contact, keep an eye out for job openings that meet your needs, and introduce you to a hiring manager looking for someone just like you. It Will All Work Out. It May Also Take A While.All told, I’ve had seven workdays that started with lots of obligations then quickly evaporated into unemployment. The good news is that it will all work out. The bad news is that there is a lot of uncertainty between your last day of work and your first day of your fancy new job when it does arrive. Using these tips will set you right as you begin your career transition. Seven Lessons From Seven Layoffs: A GuideIf you've recently been laid off, check out my book Seven Lessons From Seven Layoffs: A Guide. You can even buy the eBook to get help right now. In this book, I cover seven lessons from my seven experiences with unplanned job losses. I include my personal stories alongside practical advice for navigating this tumultuous time. You'll learn strategies for managing your mindset, finding the next right job for you, shaping your career story, and overcoming setbacks.  Learn More |

Author7-time layoff survivor Brenda L. Peterson, The Layoff Lady, waxes poetic on layoffs, job transitions, & career resilience. Buy The Book!
Were you recently laid off? Need a roadmap for what's next? Or planning just in case? Check out my book,
7 Lessons From 7 Layoffs: A Guide! Categories
All
Archives
November 2026
|